 Angel Doris
BERLIN – Germany's federal government is poised to implement sweeping reforms aimed at escalating the battle against tax evasion. Finance Minister Klingbeil and Justice Minister Hubig have announced joint plans to significantly increase penalties for tax offenders and consolidate the prosecution of such crimes, a move that includes the contentious prospect of a public registry for those found guilty.
These proposals mark a concerted effort by the coalition government to project a tough stance on financial malfeasance, responding to persistent public demand for greater accountability from individuals and corporations circumventing their tax obligations.
The core of the ministers proposals includes a substantial hike in fines and potential prison sentences for tax evasion. Officials contend that current penalties often fail to deter sophisticated schemes, leading to a perception that economic crimes are treated with undue leniency compared to other offenses.
Justice Minister Hubig emphasized the critical need for centralization in prosecuting complex financial crimes. The aim is to create specialized units with enhanced resources and expertise, ensuring a more consistent and effective application of justice across federal states, rather than the fragmented approach currently in place.
Perhaps the most provocative element of the proposed reforms is the concept of a public registry for tax offenders, a so-called public pillory. Proponents argue such a measure would serve as a powerful deterrent, leveraging public scrutiny to discourage future infractions and restore public trust in the tax system.
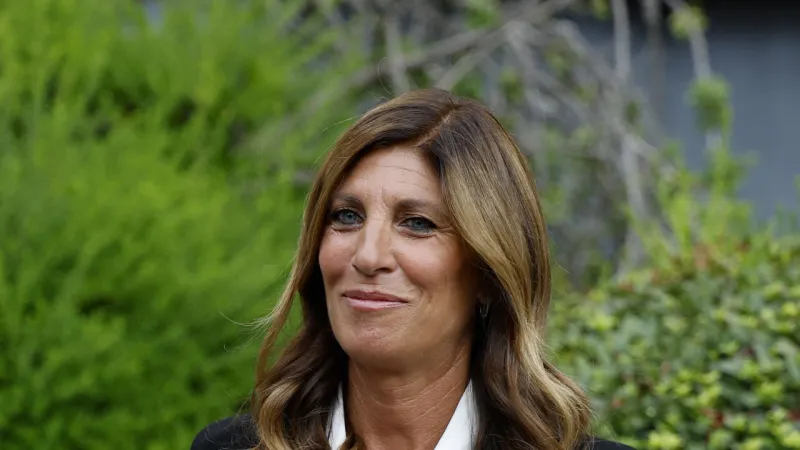
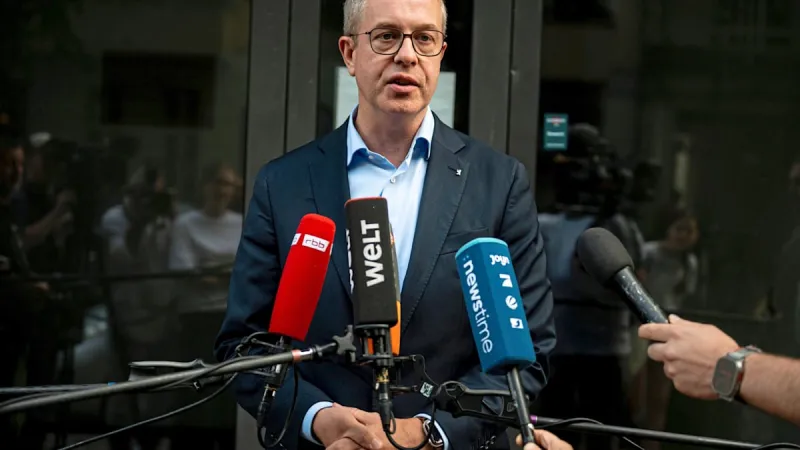
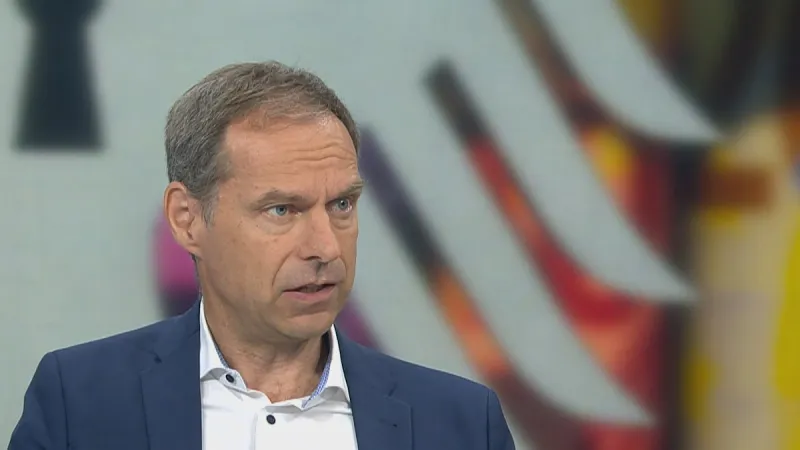
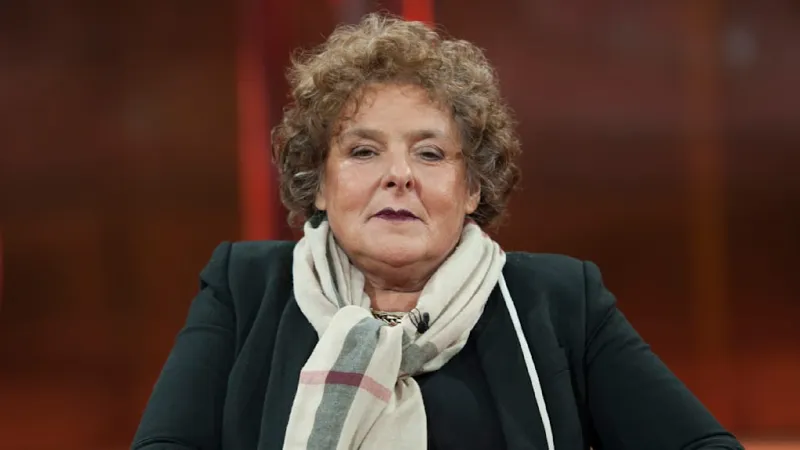
However, the initiative has met with immediate scrutiny from legal experts and former prosecutors. Margrit Lichtinghagen, a prominent former state prosecutor interviewed by WELT, voiced significant reservations about the breadth of the proposed public shaming mechanism.
Lichtinghagen articulated that while the intent to deter tax evasion is commendable, the application of a public registry should be carefully considered. She stated, The measure of a public registry must be reserved for large institutions and systematic fraud, not for individual, smaller cases that could irreparably damage lives.
Her concerns highlight the delicate balance between punitive deterrence and the potential for disproportionate impact on individuals, particularly those whose offenses, while illegal, do not represent large-scale organized crime. The former prosecutor suggested that a blanket approach risks blurring the lines between different degrees of financial misconduct.
The debate extends to the practicalities of implementation, including legal challenges related to privacy rights and the criteria for inclusion on such a list. Critics also question the effectiveness of public shaming as a primary deterrent compared to robust investigative capabilities and swift, decisive legal action.
Supporters of the tougher measures argue that the economic damage caused by widespread tax evasion necessitates an aggressive response. They point to significant revenue losses that could otherwise fund public services and infrastructure, advocating for any legal means to curb such practices.
Moreover, the proposed centralization of prosecution is expected to streamline investigations that often span multiple jurisdictions, allowing for a more unified strategy against intricate cross-border tax schemes. This approach aims to reduce bureaucratic hurdles and accelerate case resolutions.
As the legislative process unfolds, these proposals are anticipated to spark intense debate within parliament and among legal scholars. The government's challenge will be to craft legislation that is both effective in combating tax evasion and adheres to principles of fairness and due process.
The discussions underscore a broader societal reckoning with financial integrity and the role of the state in enforcing economic laws. The outcome will likely redefine the framework for accountability in Germany's financial sector for years to come.