 Edward DP Situmorang
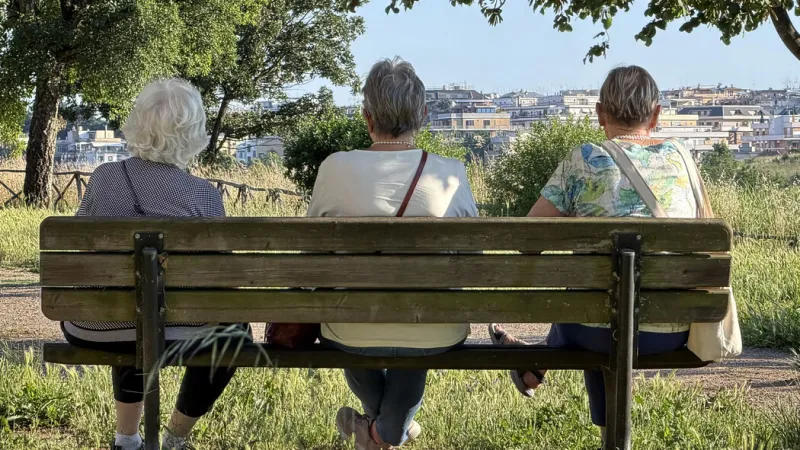
ITALY – Womens pension benefits in Italy average a staggering 34% less than those of men, a critical revelation that underscores deep-seated economic disparities within the nations social security system. This substantial gap is primarily a direct consequence of lower average lifetime earnings for women and pronounced differences in private sector remuneration, according to recent analyses.
The stark disparity translates into significantly diminished financial security for women during their retirement years. For those employed in the private sector, the gap becomes even more pronounced, with womens pensions often plummeting by approximately one-quarter compared to their male counterparts. This data points to systemic issues beyond individual career choices, reflecting broader economic structures and societal roles.
Experts attribute a significant portion of this imbalance to the persistent gender pay gap. Throughout their working lives, women frequently earn less than men for comparable work, accumulate fewer years of full-time employment due to caregiving responsibilities, and are more often concentrated in lower-paying industries or part-time positions. These factors cumulatively impact the total contributions made to their pension funds.
The effect of career interruptions, such as maternity leave or time taken for family care, further exacerbates the problem. While these breaks are often necessary, current pension calculation models do not fully compensate for the reduced contribution periods, leading to lower accumulated benefits upon retirement. This structural disadvantage disproportionately affects women.
Furthermore, the concentration of women in certain segments of the private sector, often characterized by lower wages and less robust collective bargaining agreements, contributes significantly to the observed pension chasm. These employment patterns limit opportunities for higher earnings and, consequently, robust pension accrual.
The issue of pension adequacy for women has become a focal point for policymakers and social advocates. Addressing this disparity requires a multi-faceted approach, including initiatives aimed at closing the gender pay gap, enhancing work-life balance policies, and potentially reforming pension contribution mechanisms to better account for non-continuous career paths.
This Italian experience resonates with broader European discussions on pension reform and gender equity. Similar challenges are observed in other nations striving to ensure sustainable and equitable retirement systems. For instance, the ongoing debate in Germany regarding pension overhauls and early retirement highlights shared concerns about long-term financial stability for all citizens. Readers interested in European pension reforms can find more information in the article Bas Pushes SPD on Pension Overhaul Amid Early Retirement Debate.
The economic implications extend beyond individual households, posing challenges for national social welfare systems. A large segment of the retired population facing financial precarity can strain public services and increase demands for social assistance, placing pressure on government budgets.
Advocacy groups are intensifying calls for legislative action to mitigate these disparities. They propose measures such as mandatory pay transparency, increased investment in childcare and elder care infrastructure to support womens workforce participation, and re-evaluation of pension formulas to ensure fairness.
The long-term goal is to achieve a pension system that accurately reflects an individuals overall contribution to society, irrespective of gender. This requires a shift in both employer practices and governmental policy to dismantle the structural barriers that currently disadvantage women in retirement.
Ensuring financial dignity for all retirees is not merely an economic imperative but a matter of social justice. The 34% pension gap serves as a stark reminder of the work that remains to be done in achieving true gender equality within the economic sphere, particularly as populations age and retirement becomes a larger segment of life.
The current findings demand immediate attention from legislative bodies and social partners to design and implement effective interventions. Failure to act risks entrenching a cycle of economic vulnerability for generations of women, undermining broader efforts towards a more equitable society.
This pervasive issue reflects a culmination of lifetime economic disadvantages, from starting wages to career progression and retirement benefits. Understanding these interconnected factors is crucial for crafting impactful and sustainable solutions that can meaningfully close the pension gap for women across Italy and potentially serve as a model for other nations facing similar challenges.