 Debby Wijaya
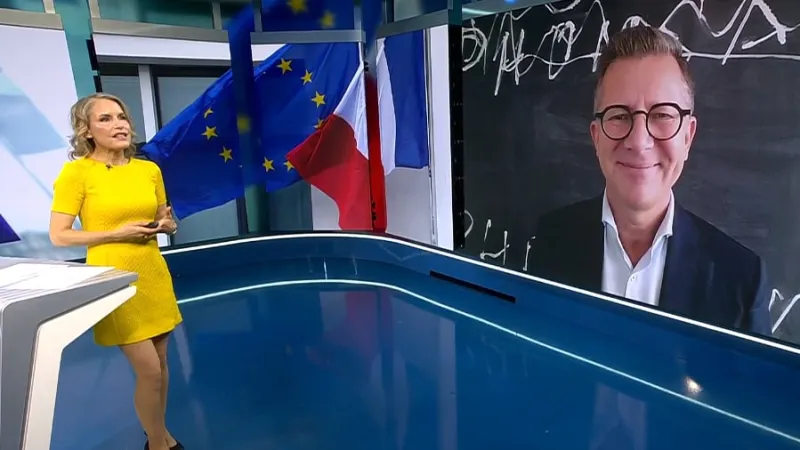
PARIS — French government bond yields have surged to 4.96 percent, marking their highest level since July 2002 and signaling a palpable increase in investor anxiety regarding the nation's economic stability. This significant escalation reflects a growing risk premium demanded by investors, closely scrutinizing France's fiscal outlook amid broader European economic uncertainties.
This spike represents a critical benchmark, pushing the cost of borrowing for the French government to levels not witnessed in nearly a quarter-century. The trajectory of these yields offers a direct window into market confidence, or lack thereof, concerning a countrys financial health and its capacity to service its debt.
Portfolio Manager Ascan Iredi articulated the severity of the situation. “This shows how much investors fear for their money,” Iredi stated, underscoring the deep-seated apprehension permeating financial markets. The demand for a higher yield essentially means investors require greater compensation for the perceived risk of holding French government debt.
The underlying causes for this heightened investor fear are multifaceted. Concerns range from internal budgetary pressures and potential political shifts within France to broader economic headwinds impacting the Eurozone. Analysts are closely watching how French policymakers will respond to this escalating cost of capital.
This development does not occur in isolation. The European financial landscape has recently seen similar tremors. For instance, the Milan Stock Exchange retreated, and an oil plunge widened sovereign spreads elsewhere, indicating a generalized sensitivity to economic pressures across the continent. Such interconnectedness means financial stress in one major economy can ripple through the entire region.
The ramifications for France are considerable. Elevated bond yields directly translate into higher borrowing costs for the government, potentially straining public finances further at a time when budget deficits are already a point of contention. This could necessitate difficult decisions regarding public spending or taxation in the coming years.
Sovereign bonds are fundamental instruments governments use to fund their operations, from infrastructure projects to social programs. When the market demands a higher yield on these bonds, it implies that the government must allocate a larger portion of its revenue to debt servicing, potentially diverting funds from other critical areas.
The last time French bond yields reached comparable heights in July 2002, the Eurozone was navigating its nascent stages while grappling with global economic uncertainties following significant market corrections. The return to such levels in 2026 suggests a renewed period of significant financial scrutiny for one of Europe's largest economies.
Moreover, the wider European context remains complex. Leaders like Italian Prime Minister Giorgia Meloni have consistently pressed the EU for fiscal flexibility amidst soaring inflation, highlighting ongoing debates about budgetary rules and economic stability across the bloc. France's current situation adds another layer of urgency to these discussions.
The challenge for the French government is now twofold: to reassure investors of its long-term fiscal prudence and to navigate the immediate economic pressures. The trajectory of these bond yields will serve as a crucial barometer of its success in addressing these concerns.
The sustained climb to 4.96 percent signifies that financial markets are applying a substantial risk premium to French debt. This elevated cost of capital is a clear indicator that the global investor community is actively re-evaluating the perceived safety and stability of investing in France, marking a pivotal moment for its economic policy.