 Chandra Wijayanto
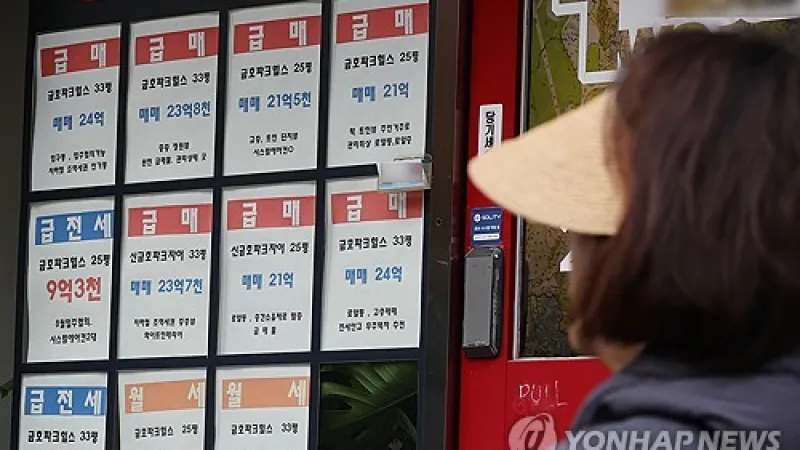
SEOUL, Nov. 16 (Yonhap) -- The number of homeowners in South Korea increased by 2.1 percent in 2025, signaling an expanding base of property ownership across the nation. This notable rise comes despite a concurrent decrease in the share of individuals holding multiple residential properties, indicating a potential shift in the countrys real estate landscape.
The latest statistics, compiled from comprehensive national surveys, reveal that approximately 12.3 million households owned at least one home in 2025. This figure represents a robust increase from the preceding year, underscoring a growing aspiration for, and attainment of, primary homeownership among the populace.
Conversely, the proportion of individuals owning two or more homes experienced a downturn. This trend suggests a potential cooling of investment-driven multiple property acquisitions or a strategic divestment by some multi-property owners. Analysts are examining whether this reflects tighter regulations, shifting market dynamics, or broader economic factors influencing asset allocation.
The data emerges at a critical juncture for the South Korean economy, which has navigated various domestic and global challenges. Economic policies aimed at stabilizing housing markets and promoting equitable access to housing may be contributing to these observed shifts.
Experts suggest that the rise in individual homeownership, alongside a decline in multiple property holdings, could foster greater housing stability for a broader segment of the population. This could alleviate some pressures associated with speculative real estate investments and affordability concerns.
Government initiatives, including efforts to enhance housing welfare and curb real estate speculation, have been central to policy discussions. These measures often aim to ensure that housing remains accessible and that the market operates without undue volatility.
The demographic composition of new homeowners is also a key area of study. Preliminary analyses indicate a diverse group, including younger families and first-time buyers, entering the market. This demographic spread suggests a broad-based push towards establishing residential roots.
Financial institutions have also played a role, with some offering more accessible mortgage products and incentives for first-time buyers. These supportive financial frameworks can significantly lower barriers to entry for individuals aspiring to own their homes.
While the exact causes for the decline in multiple property ownership are multifaceted, potential factors include increased property taxes on secondary residences and heightened regulatory scrutiny on landlords. Such policies are often designed to discourage excessive property accumulation and encourage more productive uses of capital.
This rebalancing of the housing market could have long-term implications for wealth distribution and social equity. A more distributed pattern of homeownership can reduce economic disparities and foster a greater sense of community stability. However, the broader economic context remains crucial, as highlighted in discussions concerning the South Korea Industry Crisis.
Further analysis will be required to ascertain the full impact of these trends on household debt, consumer spending, and regional economic development. Understanding the nuances of these changes is vital for policymakers to craft effective future housing and economic strategies.
Market observers will closely monitor these statistics in the coming quarters, particularly for their potential influence on housing prices, rental markets, and the overall stability of the nation's financial system.